Holiday Dream Fund: Save for Your Next Getaway
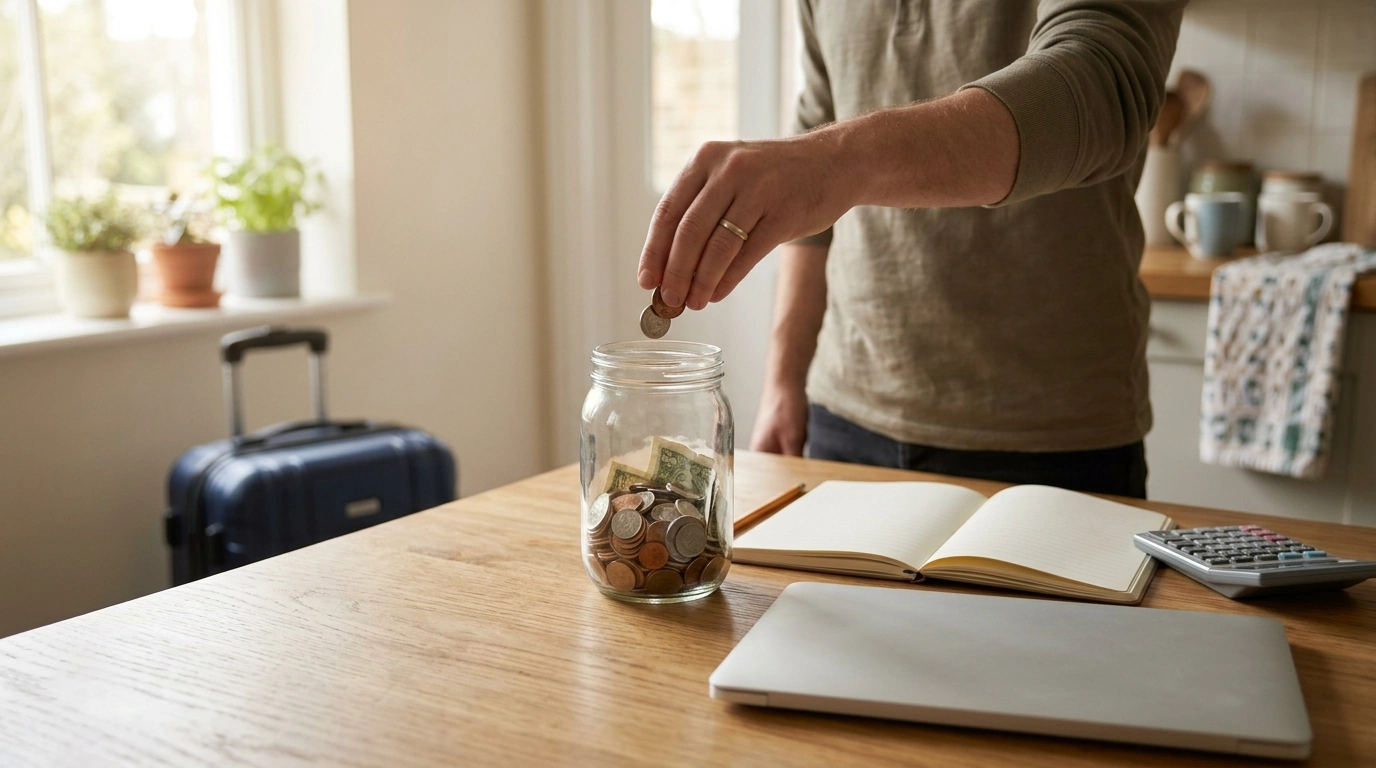
A trip feels more relaxing when it’s already paid for. A dedicated “holiday dream fund” turns vague travel goals into a clear monthly plan, keeps everyday spending from stealing your budget, and helps avoid last-minute debt. Below is a practical, low-stress system to set a target, automate savings, trim costs without feeling deprived, and map a trip budget that matches real prices.
What a holiday dream fund is (and why it works)
A holiday dream fund is a separate savings goal earmarked only for travel—ideally kept in its own savings account or a dedicated budget category. The separation is the point: when travel money is mixed with “general savings,” it’s easier to borrow from it for everyday wants and harder to see real progress.
This system works because it flips the usual pattern. Instead of hoping there’s “leftover” money at the end of the month, you pay the trip first. Saving becomes automatic, decision fatigue drops (you’ve already decided the amount per payday), and you’re less likely to lean on credit cards for flights, hotels, baggage fees, and other easy-to-miss extras.
Set a realistic trip target in 15 minutes
Start with the two details that drive most costs: destination and travel window. Prices can swing dramatically by season, school breaks, and major events. Once those are set, estimate the “big three”: transportation, lodging, and daily spending (food, local transit, and activities).
Next, add a buffer line—commonly 10–20%—so a small price bump or unexpected fee doesn’t force debt. Finally, decide what counts as “trip cost” for your fund: passports or visas, pet care, travel insurance, new luggage, souvenirs, parking at the airport, and anything else that’s likely to hit before or during the trip.
Quick travel budget framework
| Budget line | What to include | Tip to estimate quickly |
|---|---|---|
| Transportation | Flights/train, baggage fees, airport transfers, fuel/tolls | Check typical prices for your month; add baggage/seat fees |
| Lodging | Hotel/hostel/rental, taxes, resort fees | Use average nightly rate × nights; don’t forget taxes/fees |
| Food | Groceries, cafes, dining out | Set a daily amount and multiply by days |
| Local transit | Metro/bus, rideshare, parking | Look up day passes or typical rideshare costs |
| Activities | Tours, museums, events | List 3–5 must-dos and price them; add a small “spontaneous” pot |
| Travel protection | Insurance, refundable bookings premium | Price a basic policy; weigh cost vs risk |
| Buffer | Unexpected costs | 10–20% depending on complexity of the trip |
Turn the target into an automatic savings plan
Choose a deadline that’s earlier than departure—typically 2–4 weeks before you leave—so major bookings can be paid before the trip. Then calculate a simple contribution amount:
(Total trip target − Current saved) ÷ Number of pay periods
Automate transfers for the day you get paid. Treat it like a bill that can’t be “skipped casually.” If your income is irregular, automate a smaller baseline transfer and top it up whenever you’re paid.
Windfalls can move the needle fast. Tax refunds, bonuses, cash-back redemptions, gift money, or even a returned purchase can be redirected into the fund to shorten the timeline or upgrade the trip without stress.
Find money to fund the fund (without wrecking daily life)
Start with a 7-day spending snapshot. The goal isn’t perfection—it’s spotting one or two “silent leaks” that don’t feel expensive in the moment (delivery fees, forgotten subscriptions, app purchases, convenience snacks, bank fees).
Trip planning choices that protect your budget
Booking order can reduce risk. When flexibility matters, consider locking refundable lodging first, then watching transportation prices until you’re comfortable buying. For air travel, keep an eye on fees and traveler rights guidance from the U.S. Department of Transportation, since add-ons can change the real total.
Avoid common budget traps that derail travel savings
Don’t forget pre-trip costs: toiletries, adapters, charging cables, medications, new luggage, and documents. If you’re flying with special items or gifts, review screening basics ahead of time through the TSA travel guidance to avoid last-minute replacements or shipping costs.
Make it easier with a ready-made digital guide
If you want a structured setup without building spreadsheets, the Holiday Dream Fund digital guide walks through estimating total trip cost, setting savings milestones, and keeping planning decisions aligned with your budget. Pair it with automatic transfers and a weekly five-minute check-in so you always know whether you’re on track.
For transportation decisions—especially when you’re debating rentals, rideshares, and pay-as-you-go options—the Is Carsharing the Right Choice for You guide can help you compare real-world costs and avoid “transportation creep” during the trip.
Stretch the budget with smarter transportation choices
FAQ
How much should go into a holiday dream fund each month?
Use (total trip estimate − current savings) ÷ months (or pay periods) until booking/departure, then add a small buffer so minor price jumps don’t push you into debt. If the number feels tight, extend the timeline or adjust the destination/window before cutting essentials.
Should the travel fund be a separate savings account?
Yes, a separate account or dedicated budget category reduces temptation and makes progress easier to track. Look for an option with no fees and easy transfers so the money is accessible when it’s time to book.
What’s the easiest way to stop overspending while traveling?
Split the trip into buckets: big items paid ahead (transport/lodging) and daily spending for food and activities. Set a daily cap, plan one intentional splurge, and do a quick check once per day so small purchases don’t snowball.
Recommended for you

For broader budgeting tools and plain-language guidance, the Consumer Financial Protection Bureau (CFPB) offers helpful resources you can use alongside your travel fund plan.



Leave a comment